


Advertisement
Advertisement
Banks absolutely adore their fine print — and savings accounts are certainly no exception to this rule. Many accounts present attractive interest rates, but these are typically conditional upon maintaining a minimum monthly balance, often $1,000 (as seen with the UOB One account) or even as high as $3,000 (like the OCBC 360 account). If your balance dips below this specified threshold, you will be charged a fall-below fee.
This is precisely why accounts that have no minimum balance requirement are such a fantastic relief. They are much simpler to manage, offer greater flexibility, and allow you to utilize your funds without the constant worry of incurring unexpected charges.
Ultimately, paying fall-below fees on a savings account seems as unreasonable as paying annual fees for a credit card (which, incidentally, you should always strive to have waived!). If no-annual-fee credit cards exist, it's natural to wonder if there are also savings accounts available without any fall-below fees. It's a perfectly logical question, isn't it?
Absolutely. Here is our comprehensive compilation of the best savings accounts available in Singapore that provide you with no minimum balance requirement, no fall-below fees, and ensure maximum liquidity for your funds.
1. Best savings accounts in Singapore with no minimum balance
Listed below are the savings accounts in Singapore that do not require any minimum balance.
As an important public service announcement: If you are searching for your very old-school POSB passbook account, please note it is not included in this list because it actually does come with a minimum balance requirement. If you are not in the regular habit of reviewing your bank statements and transactions at least a couple of times per month, now is an excellent time to check whether you have been consistently charged a $2 fall-below fee!
2. Citibank Basic Banking Account
The Citibank Basic Banking Account is well-suited for individuals with lower incomes who earn a monthly salary below $2,000. With this basic savings account, you receive a standard ATM card that allows for free cash withdrawals, monthly account statements, free Citibank Global Transfers, and access to other essential banking services.
You are not required to meet any minimum balance, and similarly, you do not need to pay any fall-below fee. However, you are required to pay a $2 fee every month as an account maintenance charge. After all, there is a cost associated with the people and systems that ensure your internet banking and ATM card services operate smoothly.
3. DBS My Account
The majority of basic savings accounts from POSB and DBS (remember those traditional passbook accounts?) come with minimum balance requirements of $500, $1,000, or even higher amounts. If you have emptied out your childhood account and left it inactive to slowly diminish, be cautious! You may have been incurring a $2 fall-below fee on a monthly basis.
The sole DBS account that does not impose fall-below fees is their most fundamental account, the DBS My Account. This account is completely free and straightforward, with no age restrictions, no account fees, no minimum balance requirement, no initial deposit needed, and no service charges. It also functions as a multi-currency account, providing you access to 13 different currencies and — as you might have guessed! — no foreign exchange conversion fees. Very nice indeed.
One minor point to note: you will be charged a $2 account fee if you insist on receiving your account statements in paper format. But why would you choose to do that? Simply opt for e-Statements to enjoy $0 in account fees.
The most significant drawback is that the DBS My Account does not provide any interest earnings. If your goal is to earn interest, please take a look at our next DBS account featured below.
4. DBS Multiplier Account
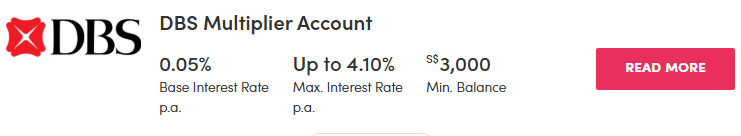
The DBS Multiplier Account technically comes with a minimum balance requirement of $3,000, but the service charge for falling below this amount is waived for customers who are under 29 years old. For others, you would have to pay a $5 fee each month.
First, let's examine what the DBS Multiplier Account offers. With the DBS Multiplier, you have the potential to earn up to 4.1 percent per annum if you credit your salary and conduct various transactions through your account:
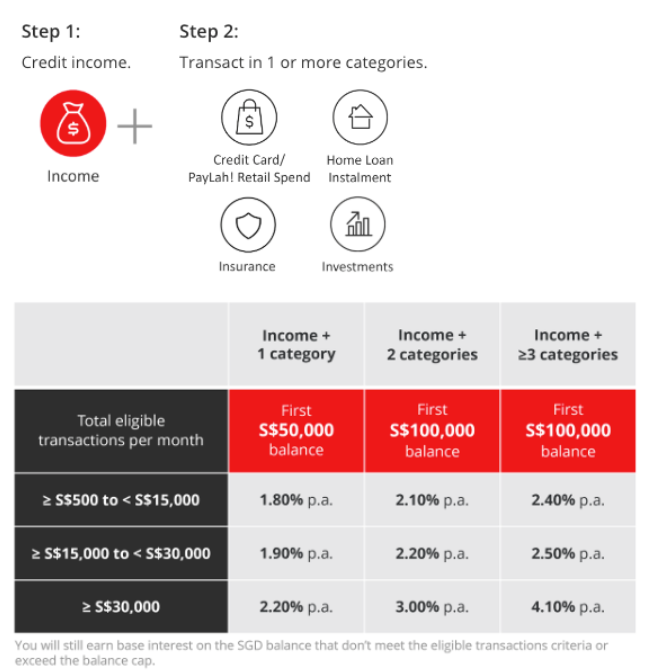
PHOTO: DBS
However, you need to see a substantial $30,000 either deposited into or withdrawn from your account every single month to unlock that 4.1 percent per annum rate. That's quite a significant requirement!
So, what DBS has done is create an exception for younger individuals to enjoy the benefits of the DBS Multiplier without having to meet all its standard requirements. If you are 29 years old or younger, you earn 1.50 percent per annum on your first $50,000 with any credit card or PayLah! spending.
If you are a young adult just beginning your financial journey, consider the DBS Savings Account for Fresh Grads and Young Adults programme, which comes with a 1.8 percent interest rate. Essentially, it is a DBS Multiplier account that includes special perks for young adults. Similar to the standard DBS Multiplier, fall-below fees are waived until you reach the age of 29.
It is important to note that once you turn 29 years old, you will be subject to the full set of requirements for the DBS Multiplier account — including the minimum balance requirement.
5. Maybank SaveUp Account
There is only one savings account at Maybank that has no minimum balance or fall-below fee — well, at least until you reach 25 years of age. It is the Maybank SaveUp Account.
The Maybank SaveUp account, by its standard terms, imposes a minimum initial deposit of $500 and a minimum balance of $1,000. If your balance falls below this minimum, you are required to pay a $2 monthly fee unless you are under 25 years old — in which case the monthly fall-below fee is waived for you.
The SaveUp account itself does not provide any bonus interest. Instead, you will need to link your SaveUp Account to the Maybank SaveUp programme, which grants you a base interest rate of 0.25 percent.
From that point, any bonus interest you earn depends on how many financial products you take up with Maybank. These can include GIRO payments, salary crediting, credit card spending, investments, insurance policies, and loans. Fulfilling one of these conditions earns you an additional 0.30 percent per annum on your first $50,000. Taking up three different products earns you a bonus of 2.75 percent per annum on your first $50,000. The maximum effective interest rate you can potentially earn is 3.08 percent per annum.
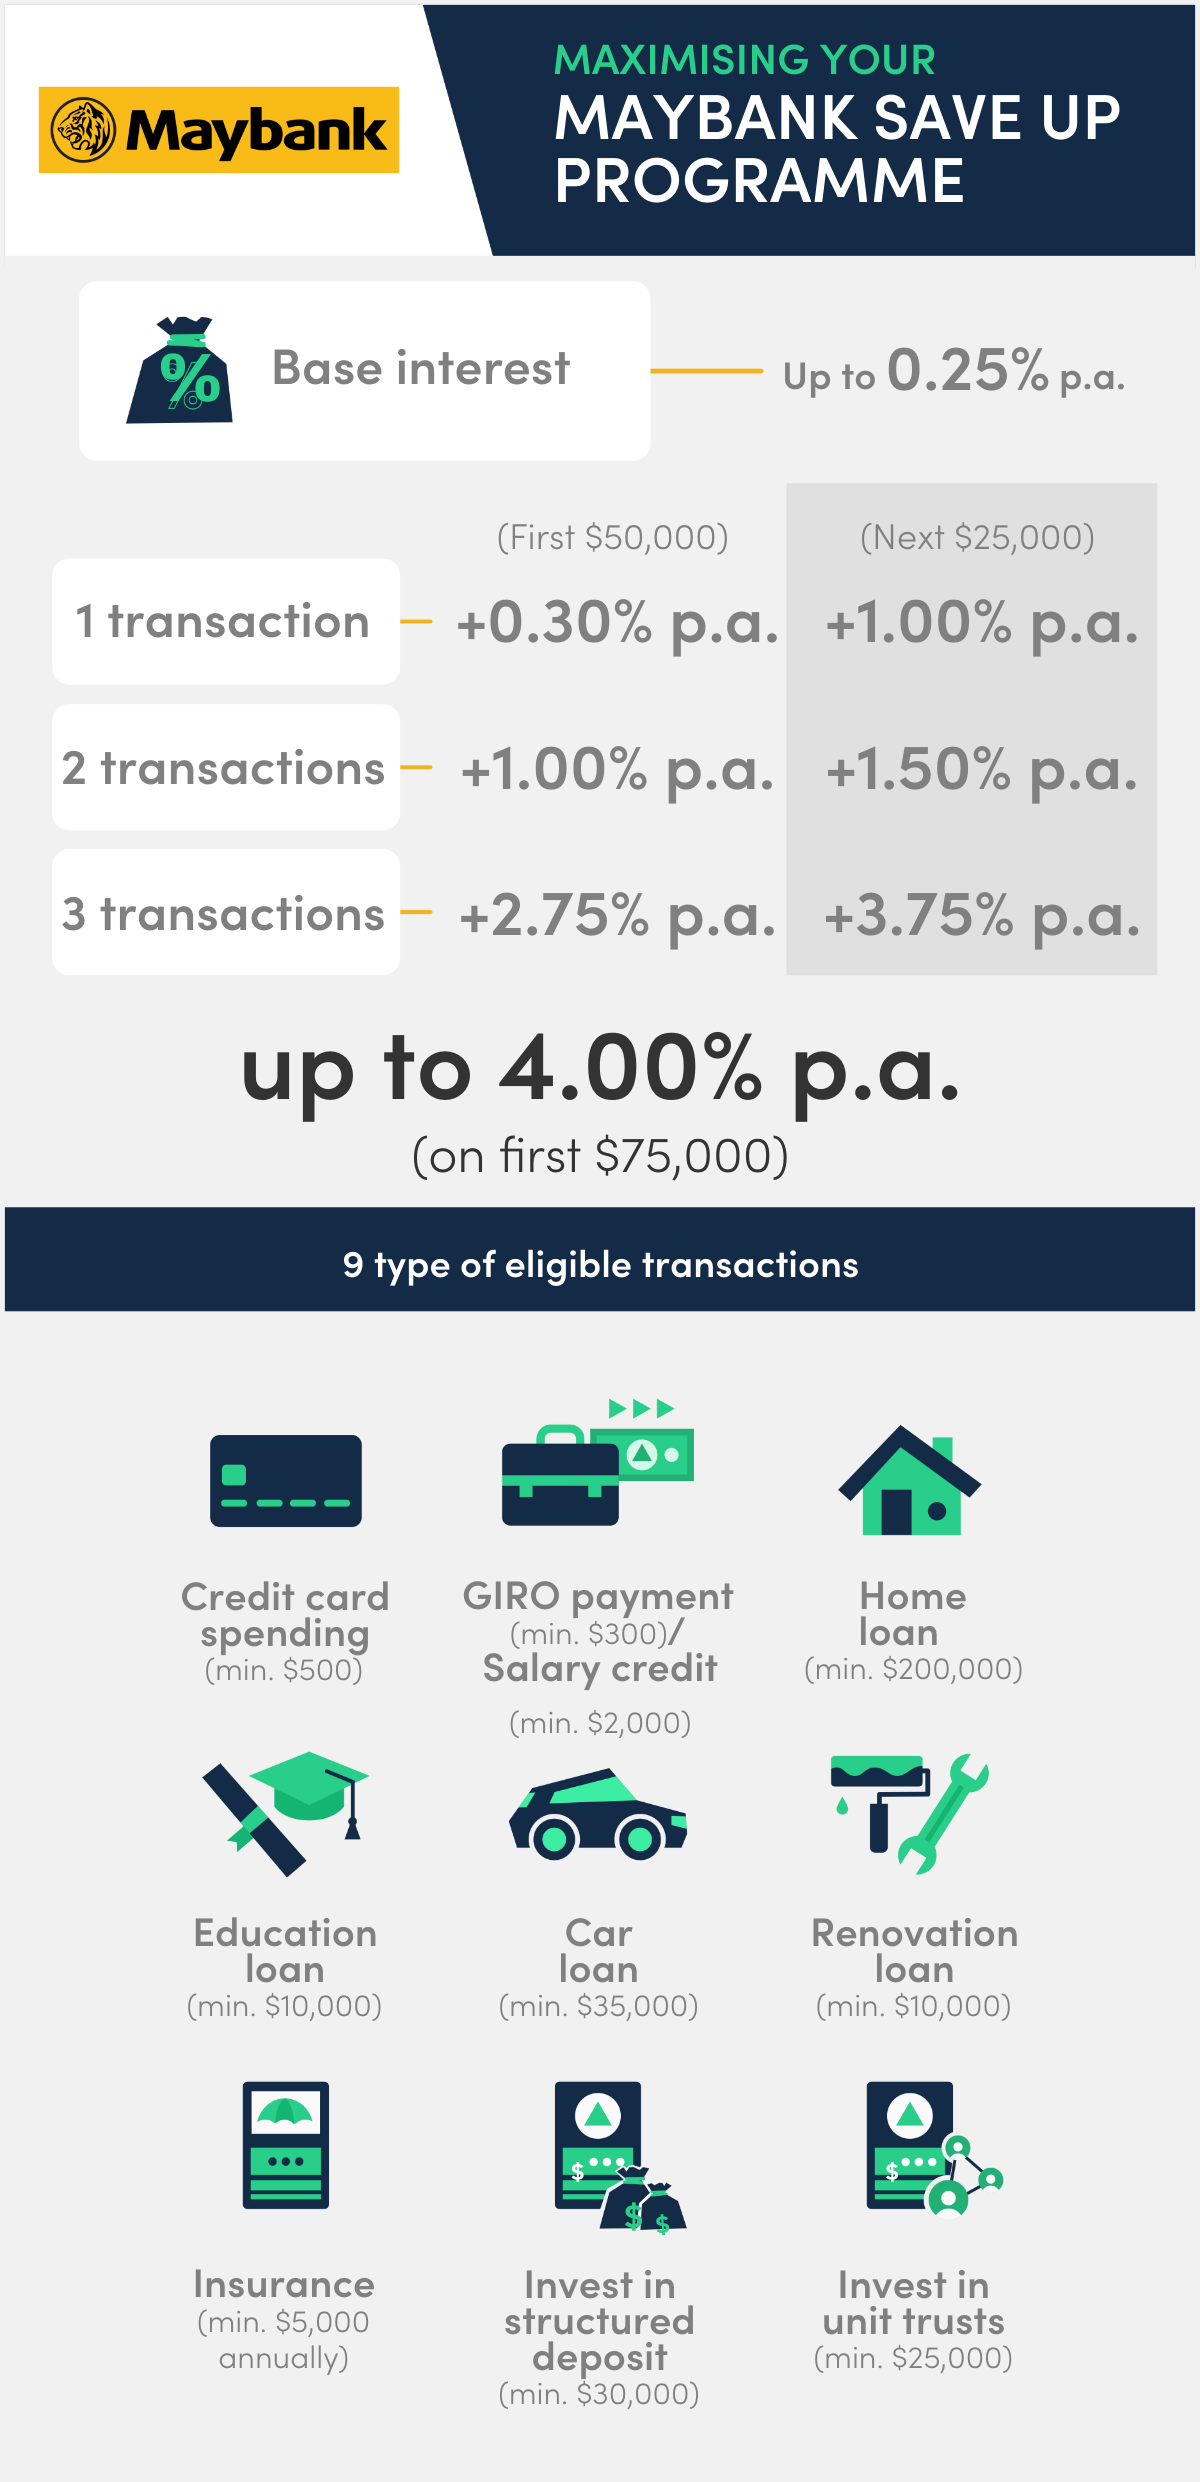
PHOTO: MoneySmart
6. OCBC FRANK Account
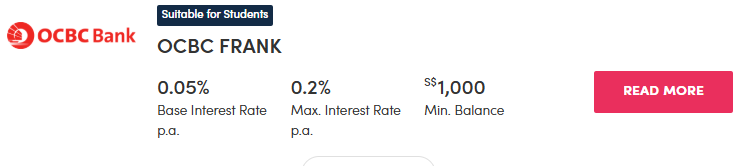
PHOTO: MoneySmart
With a very low minimum age requirement of just 16 years old, the OCBC FRANK Account is targeted towards the younger demographic (who are often somewhat financially constrained), which is likely why they have decided to implement no minimum balance and no fall-below fees… but this applies only if you are below 26 years of age. Otherwise, you will be charged a $2 fee if your account balance falls below $1,000.
On a more positive note, the account's interest rates are not as poor compared to other savings accounts of a similar type. You receive 0.1 percent per year on your first $25,000 and 0.2 percent on your next $25,000. Any amount exceeding $50,000 will earn a lower rate of 0.05 percent.
Another attractive perk is that the OCBC FRANK debit card comes with unlimited one percent cashback on purchases made at Lazada, Taobao, Shein, 7-Eleven, Cheers, Grab, SimplyGo, and several other merchants. You receive this card for free, with no annual fee charged whatsoever.
On a more superficial yet appealing level, the debit card also offers over 60 different card designs that you can choose from at no extra cost. While it is not a material financial benefit, it might still brighten your day a little.
7. RHB High Yield Savings Plus Account
The only RHB savings account that has no minimum balance requirement is the RHB High Yield Savings Plus Account, which provides you with a base interest rate of up to 1.50 percent:
There is no minimum initial deposit required and no minimum balance to maintain. The only potential charge you might face is a $30 early account closure fee if you decide to close the account within six months of opening it. It's best to avoid doing that — since there is no minimum balance required, there is absolutely no harm in leaving the account open even if you have a balance of $0 in it.
To open this account, you simply need to be a Singaporean citizen, a Permanent Resident, or a foreigner with a valid employment pass or work permit, and you must be at least 16 years old. That covers all the requirements. It's really quite straightforward!
8. Standard Chartered Basic Bank Account
With a very low minimum age requirement of just 15 years old, the traditional Standard Chartered Basic Bank Account offers affordable banking services to lower-income Singaporeans.
It provides you with a passbook, an ATM card, and free ATM withdrawals, all with a $0 minimum balance and no fall-below fee. However, similar to Citibank's basic bank account, it does come with a $2 monthly service charge regardless of your account balance. There is also an initial account opening deposit of $20 that is required.
If you are a beneficiary of the MSF Public Assistance Scheme or the Special Grant Scheme, both the service charge and the minimum initial deposit are waived for you.
9. Standard Chartered JumpStart Account
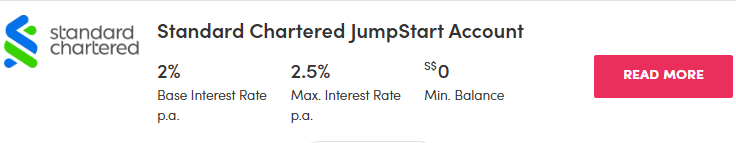
PHOTO: MoneySmart
The Standard Chartered JumpStart Account is available exclusively to young adults aged 18 to 26 years only. If you fall within this age bracket, this account is a pretty good option as it gives you one percent per annum on your account balance (up to $50,000) without requiring any effort on your part — there is no lock-in period, no minimum deposit, and no requirement for salary crediting. If you invest with Standard Chartered, you will receive an additional one percent per annum interest, for a total of two percent per annum on your first $50,000.
The account also includes a cashback debit card that provides you with one percent cashback on all eligible spending, capped at $60 cashback per month, provided you link the card to your JumpStart account. Similar to the savings account, this debit card does not have any annual fees attached to it.
10. Standard Chartered SuperSalary Account
The Standard Chartered SuperSalary Account boasts a $0 minimum initial deposit, a $0 minimum balance, and a $0 fall-below fee, which is super. What isn't so great is its not-so-super base interest rate of just 0.01 percent per annum.
Occasionally, new customers may also have the opportunity to earn bonus interest during the first few months after opening the account. The most recent promotion ran from May to December 2024 and allowed customers to earn a bonus interest of 1.99 percent per annum on their first $100,000 for the initial six months.
If a similar promotion is offered again in the future, you could consider using the account for six months to take advantage of the bonus interest, and then perhaps switch to a different account afterward. However, this strategy is only worthwhile if you have a considerable amount of cash readily available.
The account also entitles you to a Standard Chartered CashBack debit card, which enables you to earn one percent cashback on eligible spending, with a monthly cap of $60.
11. Trust Savings Account
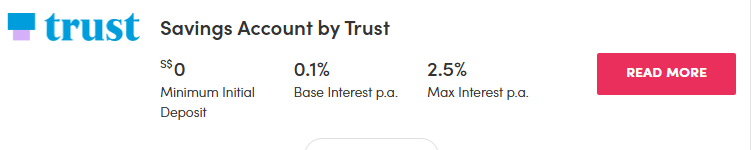
PHOTO: MoneySmart
The Trust Savings Account comes with no lock-in period, no monthly fee, no minimum balance requirement, and no account closure fee. So, when it comes to a low-commitment account, this one might just be the best option available.
With no strings attached, you get to earn 0.50 percent per annum interest on your Trust savings account under their Zen plan. Trust Bank offers three distinct plans with this savings account, and you can earn higher interest rates on their other plans by fulfilling certain specific criteria. Here is a detailed breakdown for your reference:
Trust savings account plan |
Advertisement
Advertisement


Advertisement


